Negative impactResults
Ambuja Cements Q2 net profit plunges 90 pc as margins come under pressure
Business Standard 1 hr ago·29 Oct 2026, 10:14 am
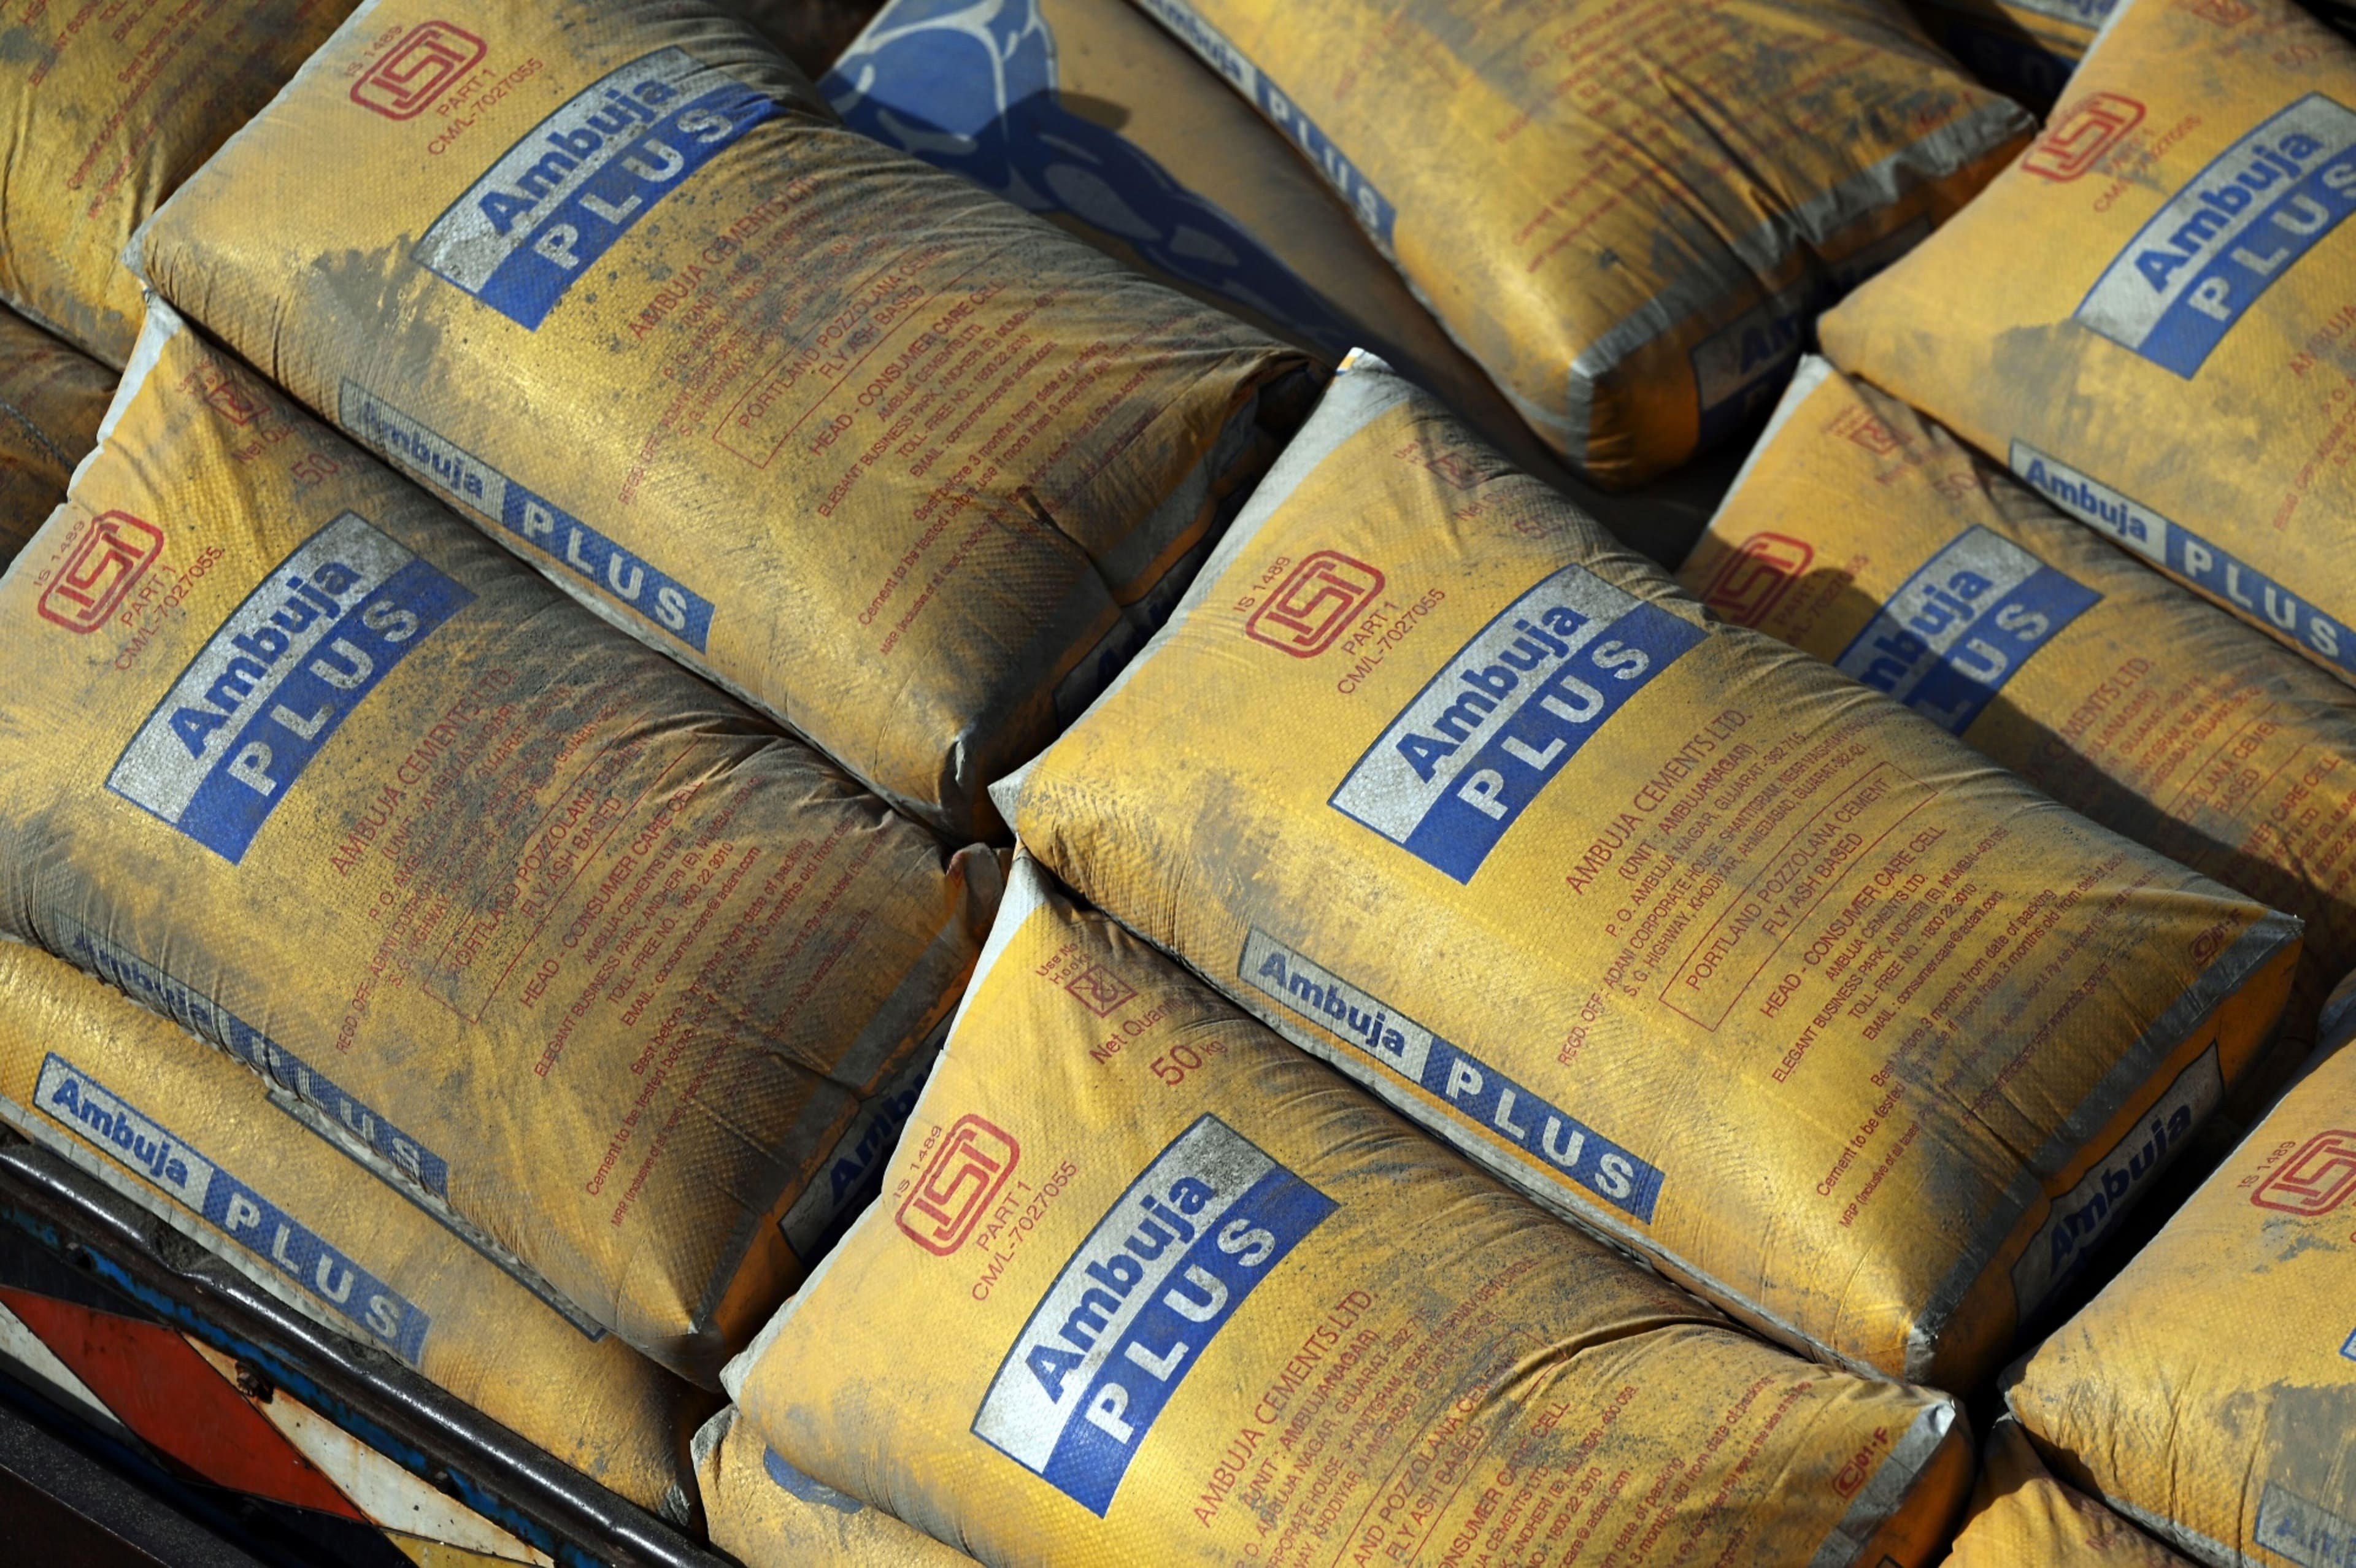
Ambuja Cements reported a significant drop in its net profit for the second quarter, falling by 90% year-on-year to Rs 236 crore. This sharp decline is primarily driven by higher costs for fuel and logistics, which have squeezed the company's operating margins. Additionally, a one-time reversal of a previous tax provision in the same period last year has made the current earnings figure appear even lower in comparison.
For investors, the key takeaway is that the company is facing a challenging operating environment marked by rising input costs and seasonal demand weakness. While revenue from operations remained relatively stable, the focus now shifts to how effectively Ambuja can manage these cost pressures and whether its margins will recover in the coming quarters. Investors should monitor future updates on raw material costs and demand trends.
Affected stocks
Bearish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns Ambuja Cements (AMBUJACEM).
- Category: Results.
- AI reads the tone as negative (potentially bearish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for Ambuja Cements worth tracking. The tone is negative — watch for downside reaction. Use the price and stock snapshot to gauge how the market is responding.