Positive impactResults
Asian Paints Q2FY27 result: Profit rises 7.5% to ₹1,068 cr, sales grow 17%
Business Standard 1 hr ago·29 Oct 2026, 10:21 am
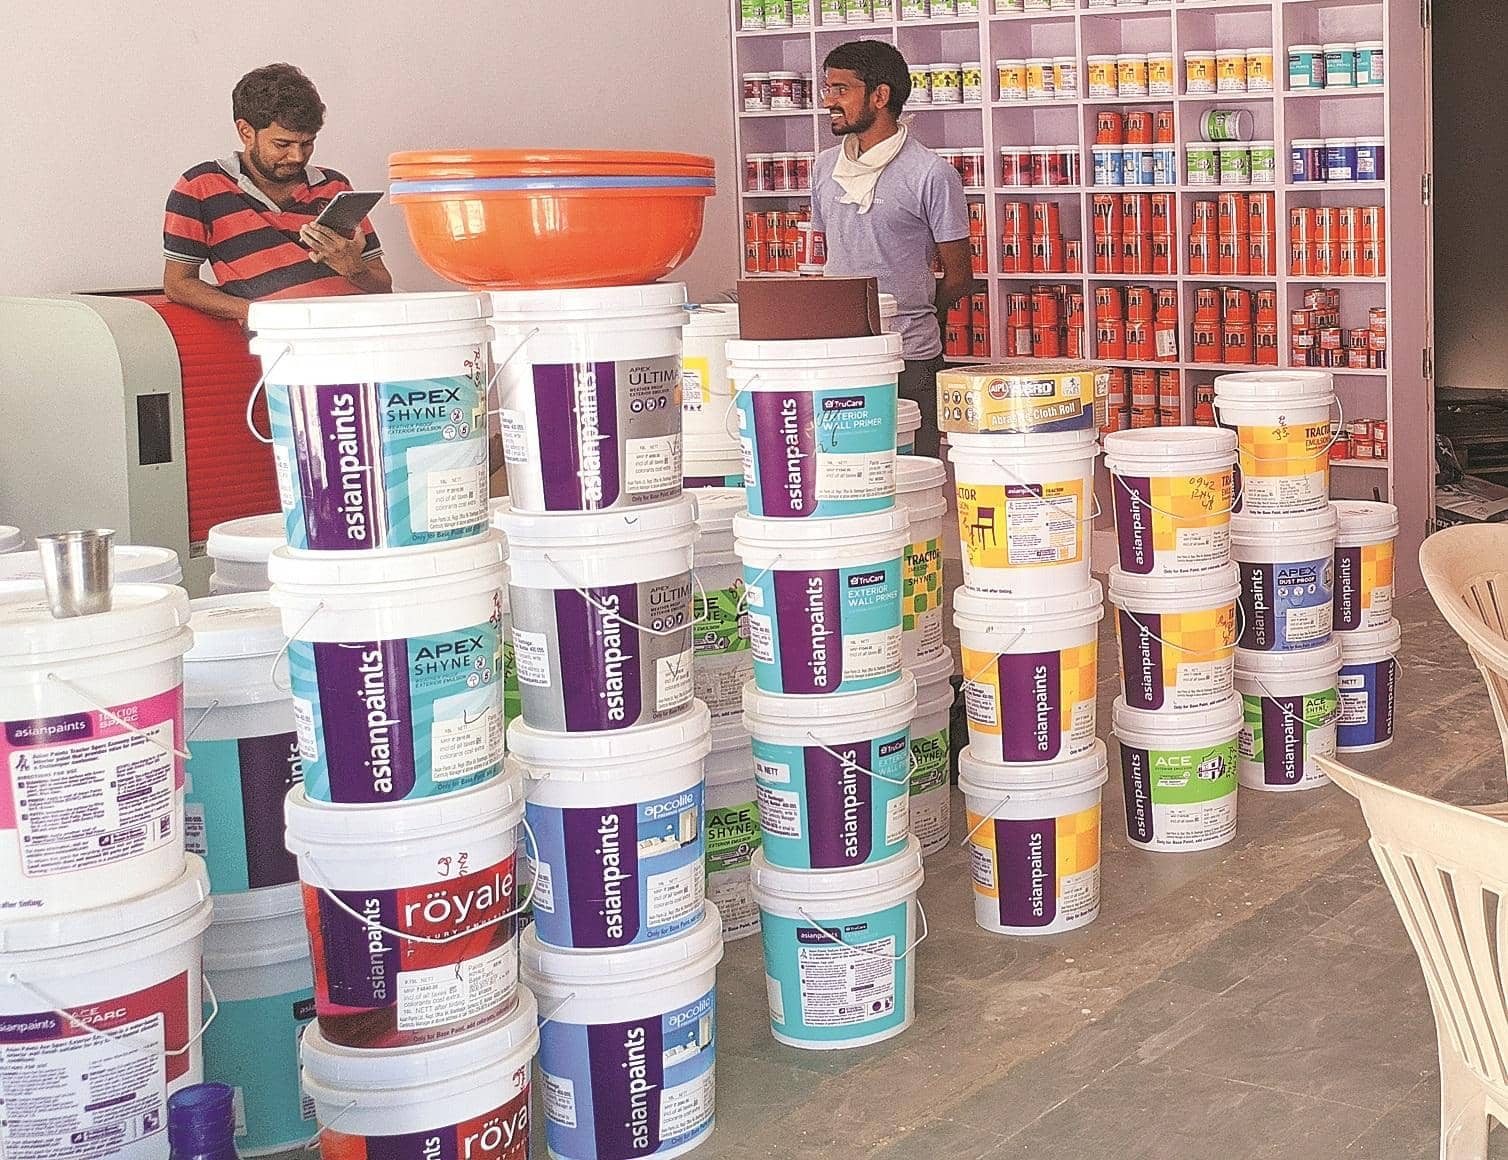
Asian Paints reported a strong Q2FY27 performance with consolidated net sales rising 17% to ₹9,954 crore. This growth was driven by healthy demand in both the domestic coatings market and its international operations. However, the company faced headwinds from higher raw material costs, which put pressure on its operating margins.
For investors, this result highlights a classic growth versus margin trade-off. While the top-line expansion is a positive sign for the company's market position, the margin pressure raises questions about the sustainability of these gains. It signals that while the business is growing, it is facing increasing input costs that could impact profitability in the near term.
Moving forward, investors should keep a close watch on the company's ability to pass on these rising costs to consumers. The upcoming quarters will be crucial to see if Asian Paints can maintain its sales momentum without severely eroding its profit margins.
Affected stocks
Bullish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns Asian Paints (ASIANPAINT).
- Category: Results.
- AI reads the tone as positive (potentially bullish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for Asian Paints worth tracking. The tone is positive — historically associated with upward pressure, though not predictive. Use the price and stock snapshot to gauge how the market is responding.