Positive impactResults
Axis Bank Q2 Preview: Profit Seen Rising 41% As FCNR Deposits Weigh On Margins
NDTV Profit 3 hrs ago·16 Oct 2026, 8:49 am
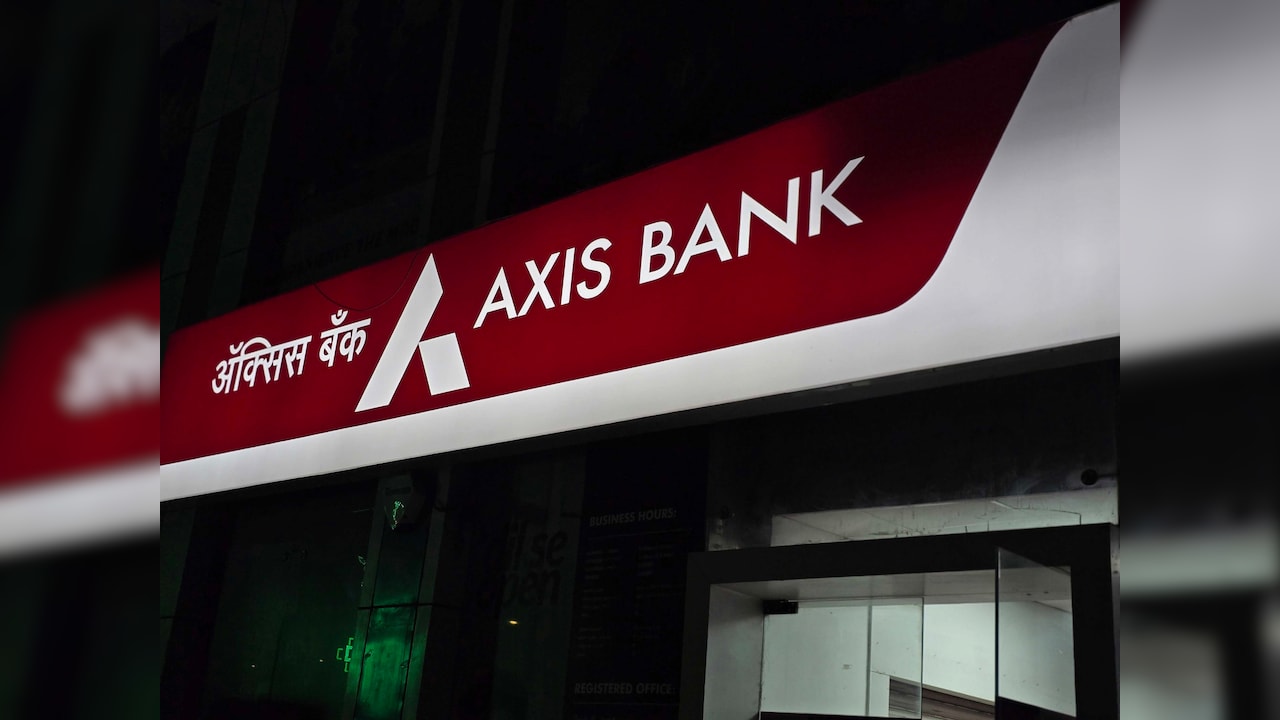
Axis Bank is expected to report a significant jump in profit for the September quarter, with analysts forecasting a 41% year-on-year rise. This optimism is primarily driven by strong growth in both its loan and deposit books. However, the bank is also facing pressure on its profitability margins. This is largely due to a higher cost of funds, stemming from increased mobilisation of Foreign Currency Non-Resident (Bank) (FCNR(B)) deposits. These deposits are generally more expensive than domestic ones, which can squeeze the net interest margin.
For investors, this mixed picture highlights the bank's resilience amidst a challenging interest rate environment. While the higher cost of deposits is a headwind, the simultaneous growth in loans suggests the bank is successfully expanding its core business. The improvement in credit costs is another positive signal, indicating that the bank's asset quality is stabilising. Investors should keep a close watch on the bank's subsequent commentary regarding its strategy to manage the cost of funds and sustain its margin growth.
Affected stocks
Bullish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns Axis Bank (AXISBANK).
- Category: Results.
- AI reads the tone as positive (potentially bullish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for Axis Bank worth tracking. The tone is positive — historically associated with upward pressure, though not predictive. Use the price and stock snapshot to gauge how the market is responding.