Neutral impactCompany
Buying a resale flat with an existing home loan? Here’s how to avoid the pitfalls
Mint 2 hrs ago·25 Sept 2026, 3:04 pm

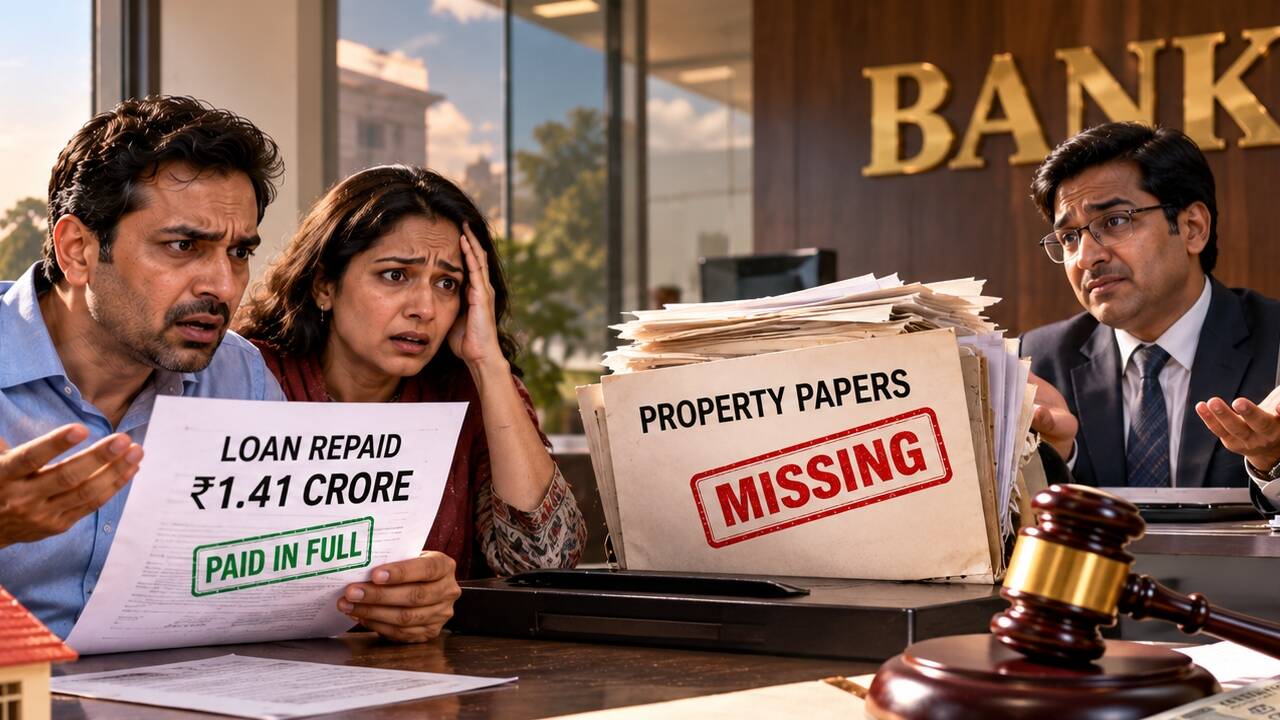
Purchasing a resale property that still has an outstanding home loan requires careful verification. The buyer must first obtain the seller's latest loan account statement or a foreclosure letter from the bank. This document confirms the exact amount owed and the interest rate, ensuring the buyer pays the correct balance at the time of transfer. It also helps identify any hidden charges or pending dues that could complicate the transaction.
For investors, this due diligence is crucial to avoid unexpected financial burdens. A discrepancy in the loan details can lead to legal disputes or financial loss. Once the loan details are verified, the buyer should coordinate with the bank to transfer the loan account to their name. This process involves submitting the sale deed and other necessary documents to the lender for approval.
Moving forward, the buyer should keep track of the loan transfer timeline and ensure all documentation is updated promptly. Staying informed about the bank's processing times and any additional requirements will help streamline the transition. Regular communication with the bank and the seller ensures a smooth transfer of ownership and liability.
Key takeaways
- Category: Company.
Why it matters
A routine update. Use the price and stock snapshot to gauge how the market is responding.