Positive impactCompany
Eternal Q2 Review: Brokerages Bet On Blinkit Growth Despite Margin Risks; Check Target Price, Potential Upside
NDTV Profit 3 hrs ago·22 Oct 2026, 2:05 am
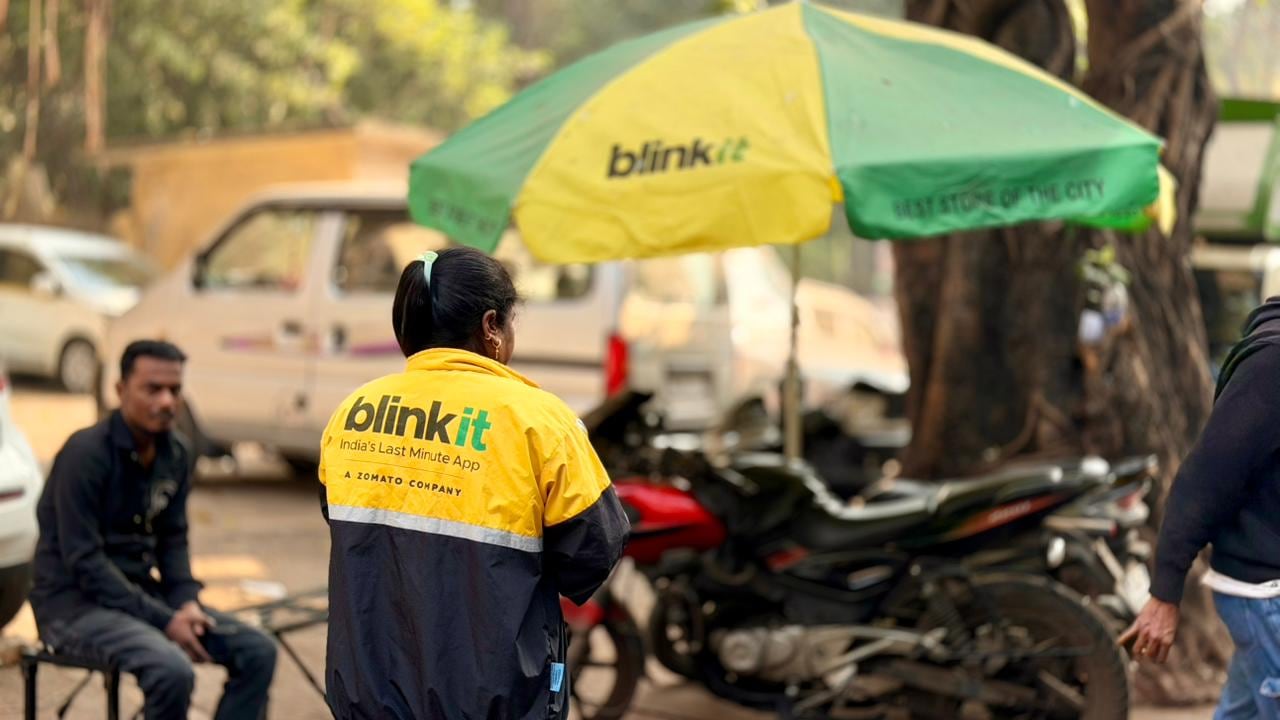
Eternal has reported its second-quarter results, highlighting strong growth in its Blinkit business. The company's delivery arm is seeing high demand, which is driving overall revenue. However, analysts have noted that this expansion comes with higher costs, creating some pressure on profit margins. Despite these challenges, brokerages remain optimistic about the long-term potential of the quick-commerce segment.
For investors, this news signals that Eternal is aggressively scaling up its operations to capture market share. The focus is now on how management plans to balance this rapid growth with cost control to maintain healthy profitability. The stock's performance will likely depend on whether the company can sustain this momentum without eroding its margins too quickly.
Moving forward, market participants should watch for updates on operational efficiency and future expansion plans. Any guidance on cost management strategies will be key. The stock's reaction will also depend on broader market sentiment towards the quick-commerce sector and how investors perceive the trade-off between growth and profitability.
Affected stocks
Bullish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns Eternal (ETERNAL).
- Category: Company.
- AI reads the tone as positive (potentially bullish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for Eternal worth tracking. The tone is positive — historically associated with upward pressure, though not predictive. Use the price and stock snapshot to gauge how the market is responding.