Positive impactCompany
Explained - Here's why HSBC expects a 33% upside on SRF shares
CNBC-TV18 1 hr ago·17 Sept 2026, 5:51 am
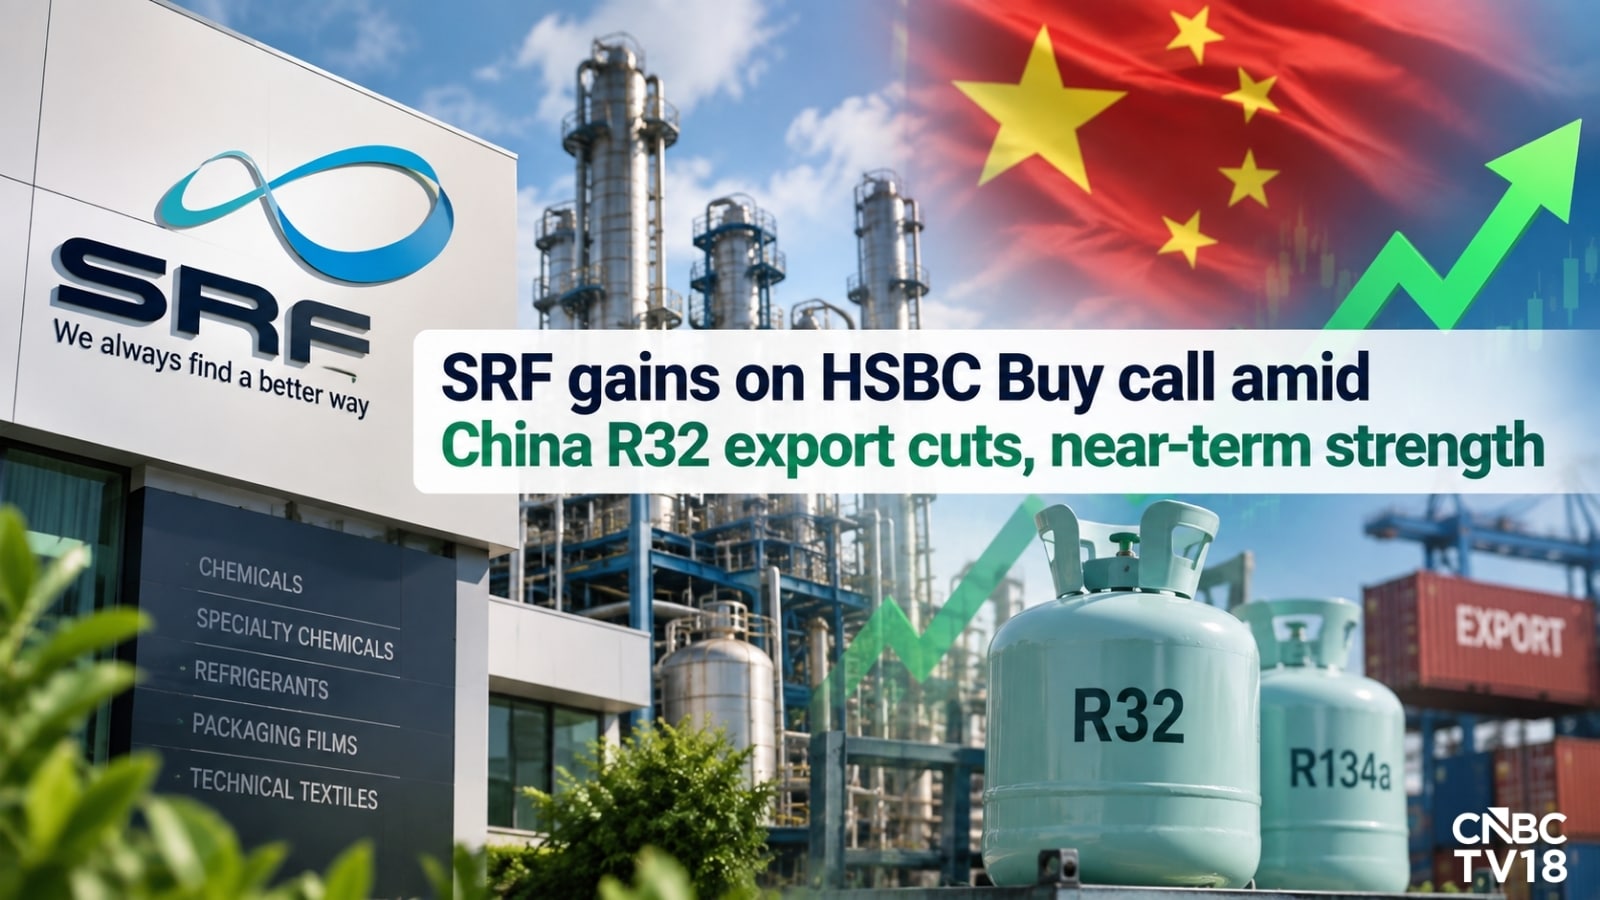
HSBC analysts have upgraded their view on SRF, projecting roughly a one‑third rise in the share price. The upgrade is anchored on two operational themes: the company’s decision to move part of its refrigerant production capacity from R32 to R134a, and an anticipated rebound in its speciality chemicals division.
Shifting quota to R134a is expected to soften the pressure from an oversupplied R32 market, helping to protect margins. At the same time, a pickup in speciality chemicals could provide a fresh earnings driver, giving the stock additional momentum.
Investors will be looking for evidence that the quota shift is being implemented on schedule, that demand for R134a remains robust, and that the speciality chemicals segment delivers higher sales. Upcoming quarterly results and any regulatory updates on refrigerants will be key signals.
Affected stocks
Bullish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns SRF (SRF).
- Category: Company.
- AI reads the tone as positive (potentially bullish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for SRF worth tracking. The tone is positive — historically associated with upward pressure, though not predictive. Use the price and stock snapshot to gauge how the market is responding.