Negative impactSector
For Tata Motors CV, The Commodity Bill Is Rising Faster Than Its Pricing Power
NDTV Profit 2 hrs ago·24 Oct 2026, 4:26 am
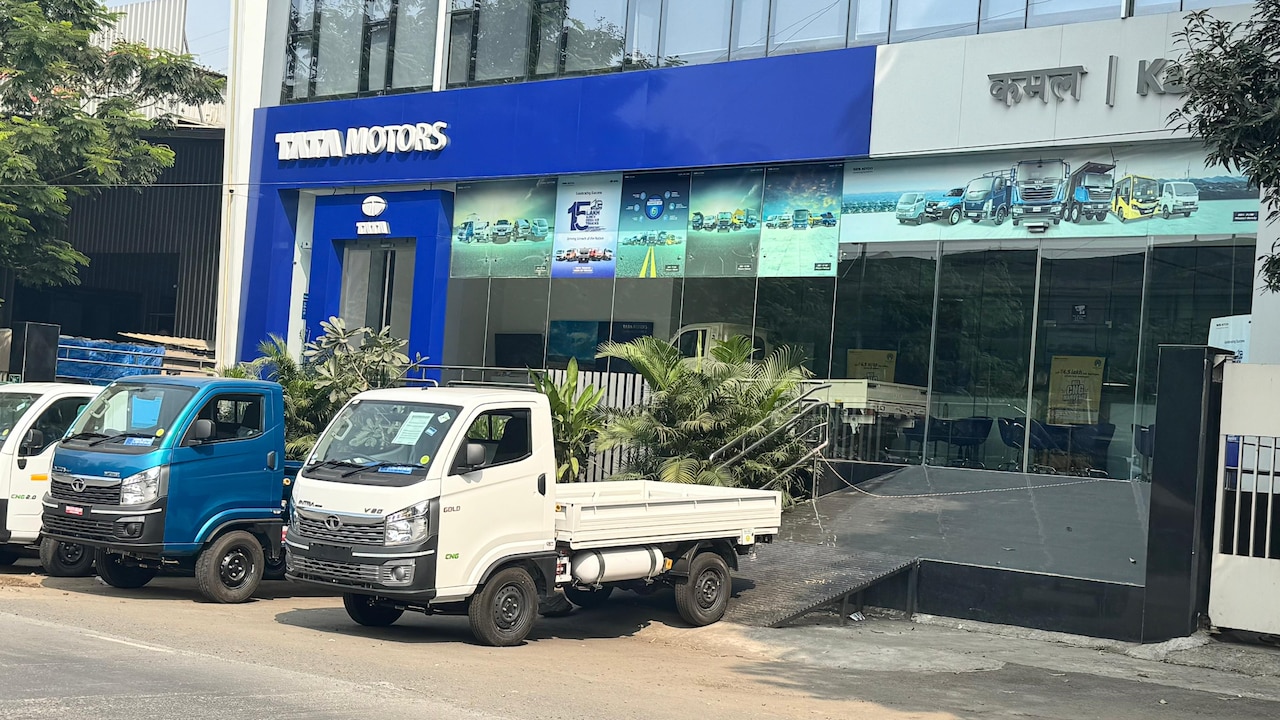
Tata Motors Commercial Vehicles (TMCV) is facing a tough operating environment as the cost of essential raw materials, such as steel, continues to rise sharply. This cost inflation is outpacing the company's ability to increase prices for its trucks and buses, squeezing profit margins in the process. The pressure is evident in the company's standalone results, which include its joint venture with Cummins.
For investors, this margin compression is a key concern, as it directly impacts the profitability of the commercial vehicle segment. The company's pricing power—the ability to pass on higher costs to customers—is currently under strain, which could limit its ability to maintain healthy earnings growth in the near term.
Investors should monitor the company's future commentary on raw material trends and its strategies to manage these costs. Keeping an eye on the broader commercial vehicle demand cycle will also be crucial to understanding how TMCV navigates this challenging phase.
Affected stocks
Bearish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns Tata Motors (TMCV).
- Category: Sector.
- AI reads the tone as negative (potentially bearish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for Tata Motors worth tracking. The tone is negative — watch for downside reaction. Use the price and stock snapshot to gauge how the market is responding.