Neutral impactSector
He got 2 flats worth Rs 1.38 crore for tenancy rights; taxman sent notice, what ITAT said
Times of India 2 hrs ago·23 Sept 2026, 7:05 am
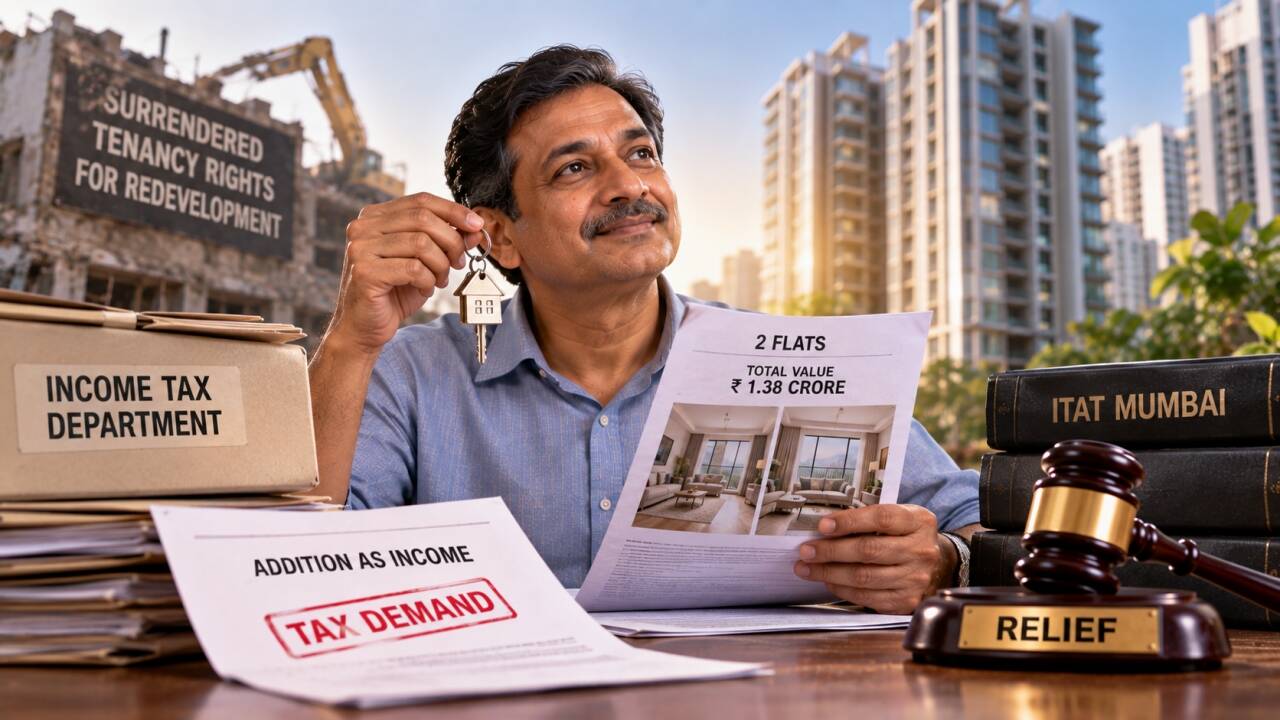
A Mumbai tenant recently received two flats worth Rs 1.38 crore in exchange for surrendering his tenancy rights during a building redevelopment. The tax department initially issued a notice demanding tax under Section 56(2)(x), which levies tax on the 'perquisite value' of any benefit received without consideration. The Income Tax Appellate Tribunal (ITAT) recently ruled in favor of the individual, stating that a tax demand cannot be imposed solely because the benefit was received in the form of property rather than cash.
This ruling clarifies that the tax liability depends on the specific nature of the transaction. For investors, this case highlights the importance of understanding how tax authorities treat non-cash benefits and perquisites. It underscores the need for taxpayers to ensure their documentation is robust and that the transaction structure is compliant with tax laws, as the taxman scrutinizes the 'perquisite value' of such benefits closely.
Moving forward, taxpayers in similar situations should be prepared to justify the valuation of the property received. Investors should watch for further guidance from the tax department on how to treat such benefits in future assessments. This case serves as a reminder that the tax implications of property transactions, especially those involving redevelopment, can be complex and require careful attention.
Key takeaways
- Category: Sector.
Why it matters
A routine update. Use the price and stock snapshot to gauge how the market is responding.