Neutral impactSector
IRDAI proposes new motor insurance rules: What could change for new car buyers
Mint 52 min ago·24 Sept 2026, 3:15 am

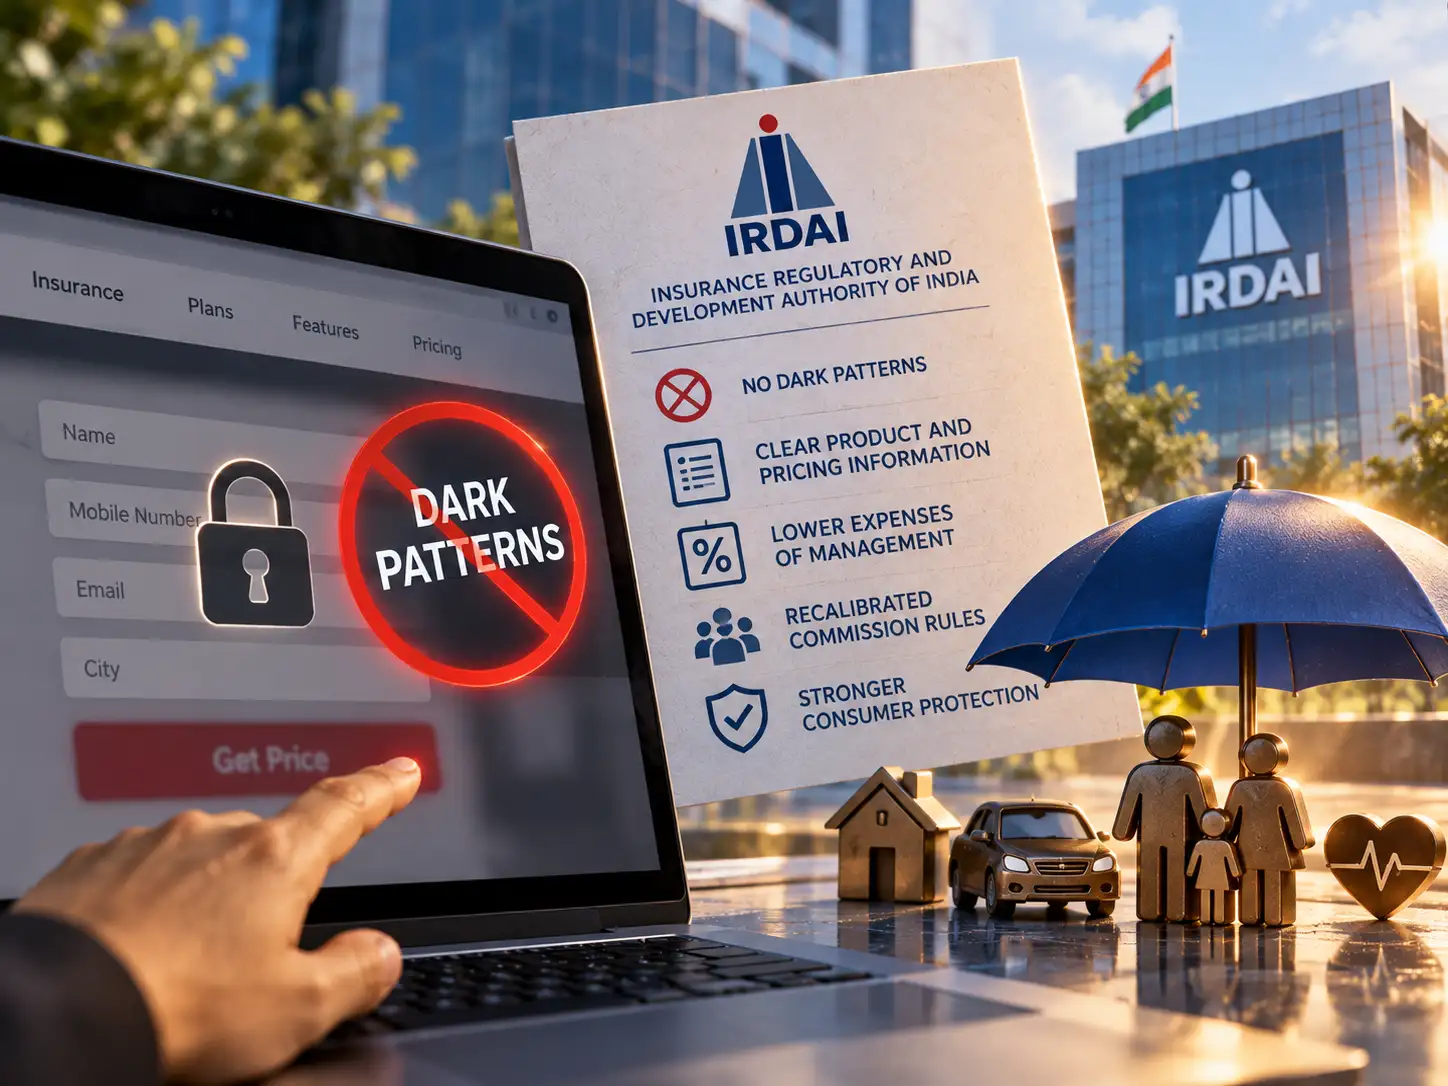
The Insurance Regulatory and Development Authority of India (IRDAI) has proposed new rules to modernize how motor insurance is sold. The key changes include allowing customers to buy policies digitally through platforms like Bima Sugam and introducing stricter compliance checks for motor dealers. Additionally, the regulator suggests lowering commissions for mandatory third-party insurance.
These measures aim to make the insurance buying process more transparent and accessible for retail investors. By reducing reliance on intermediaries and dealers, the rules could potentially lower policy costs for new car buyers over time. It also seeks to protect consumers from misleading sales tactics.
Investors should monitor the final implementation of these guidelines. If adopted, the shift towards digital distribution could impact the business models of traditional insurance brokers and motor dealers. The market will likely react to how these changes influence the overall profitability and operational efficiency of insurance companies.
Excerpt from Mint
IRDAI has proposed changes to motor insurance distribution that could alter how new-vehicle buyers purchase insurance. It proposes digital purchase options through platforms such as Bima Sugam, tighter rules for motor dealers and lower commissions on mandatory third-party motor insurance. Buying motor insurance could…Read the original at Mint
Key takeaways
- Category: Sector.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update worth tracking. Use the price and stock snapshot to gauge how the market is responding.