Positive impactCompany
SBI Q2 preview: NII to rise 11-13%; margin to hold on lower FCNR(B) flows
Business Standard 1 hr ago·2 Nov 2026, 9:24 am
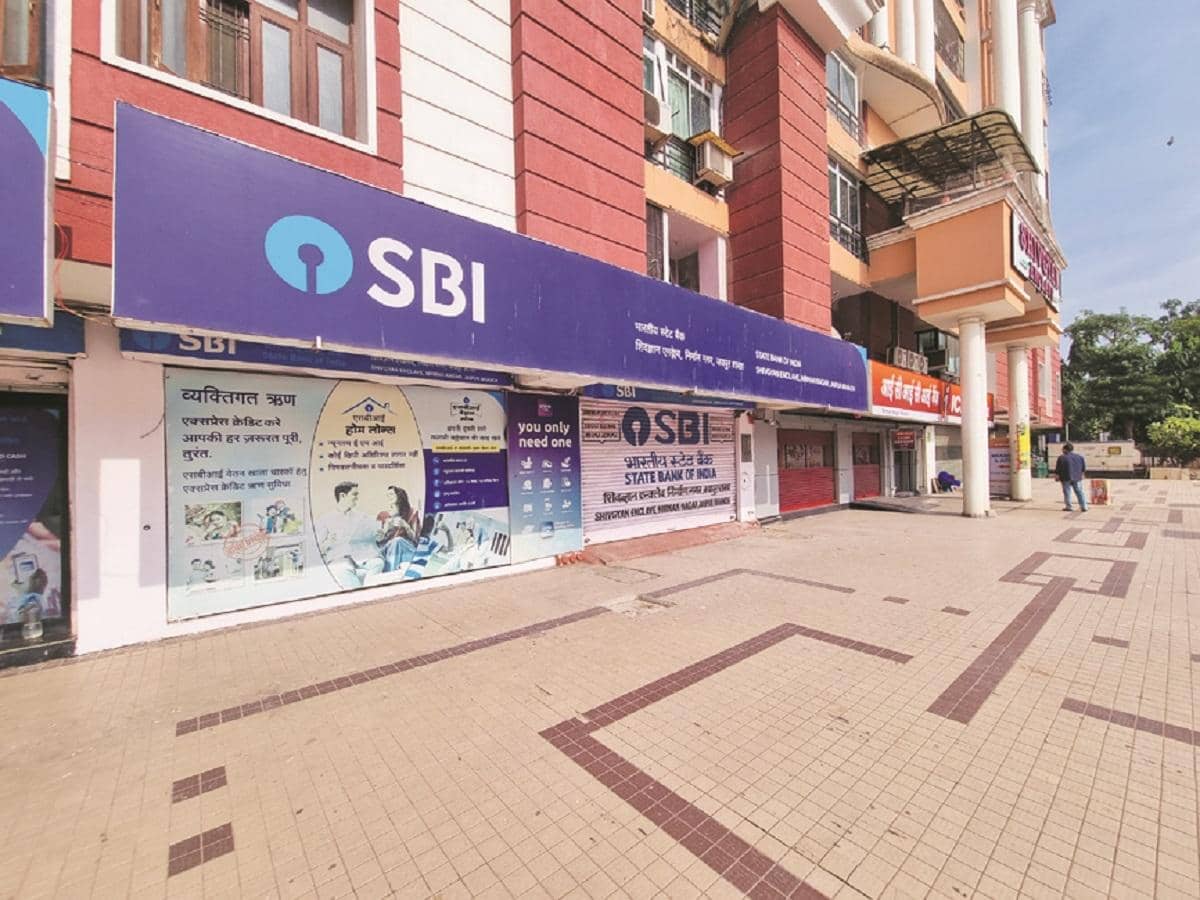
State Bank of India (SBI) is set to report its second-quarter earnings, with analysts forecasting a strong 11-13% year-on-year rise in Net Interest Income (NII). This growth is primarily driven by a higher interest rate environment, which allows banks to charge more on loans while keeping deposit costs stable. However, the bank's net interest margin is expected to remain under pressure due to the absence of fresh Foreign Currency Non-Resident (Banks) (FCNR(B)) inflows. These inflows previously helped boost margins, and their absence means the bank must manage its asset quality and cost of funds carefully.
For investors, this preview suggests SBI will likely report a solid profit growth story, supported by healthy loan demand. However, the pressure on margins indicates that the bank's profitability might not expand as aggressively as in previous quarters. The key takeaway is that while revenue is growing, the efficiency of that revenue generation is being tested. Investors should look for management commentary on how SBI plans to navigate this margin pressure and maintain its asset quality in a challenging economic environment.
Affected stocks
Bullish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns State Bank of India (SBIN).
- Category: Company.
- AI reads the tone as positive (potentially bullish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for State Bank of India worth tracking. The tone is positive — historically associated with upward pressure, though not predictive. Use the price and stock snapshot to gauge how the market is responding.