Positive impactCompany
Tata Consumer Q2 Review: Motilal Oswal Sees 28% Upside On Multiple Growth Drivers; Check Target Price
NDTV Profit 2 hrs ago·27 Oct 2026, 2:22 am
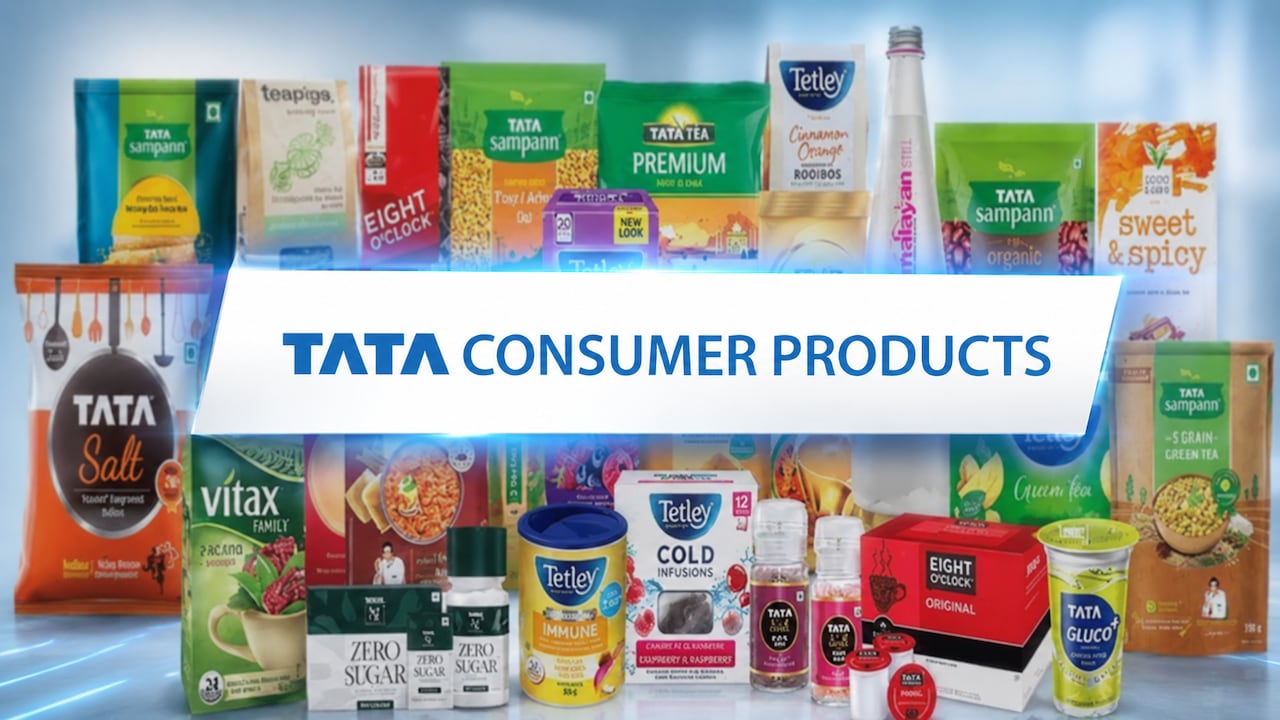
Tata Consumer Products reported a 14% year-on-year revenue growth of Rs 5,660 crore in the second quarter. The company’s performance was driven by strong demand for its packaged foods and beverages, along with better pricing power in key markets. This growth reflects the company's ability to expand its market share despite competitive pressures.
For investors, this performance signals a resilient business model with multiple growth drivers. The company’s focus on premiumization and expanding its product portfolio positions it well for sustained demand. The positive outlook suggests potential for continued earnings growth, making it a stock to watch for long-term investors.
Moving forward, investors should monitor the company’s ability to maintain margin expansion and its progress in international markets. Any updates on new product launches or strategic partnerships could further influence the stock’s performance. Keeping an eye on broader consumption trends will also be crucial for assessing the stock’s future trajectory.
Affected stocks
Bullish1 stock
Bull / bear label is derived from the article's AI sentiment — indicative, not advice. Prices may be delayed.
Key takeaways
- Concerns Tata Consumer Products (TATACONSUM).
- Category: Company.
- AI reads the tone as positive (potentially bullish) for the stock.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update for Tata Consumer Products worth tracking. The tone is positive — historically associated with upward pressure, though not predictive. Use the price and stock snapshot to gauge how the market is responding.