Neutral impactEconomy
UPI vs credit cards: What should you choose for payments after MDR?
Times of India 1 hr ago·9 Oct 2026, 1:39 pm
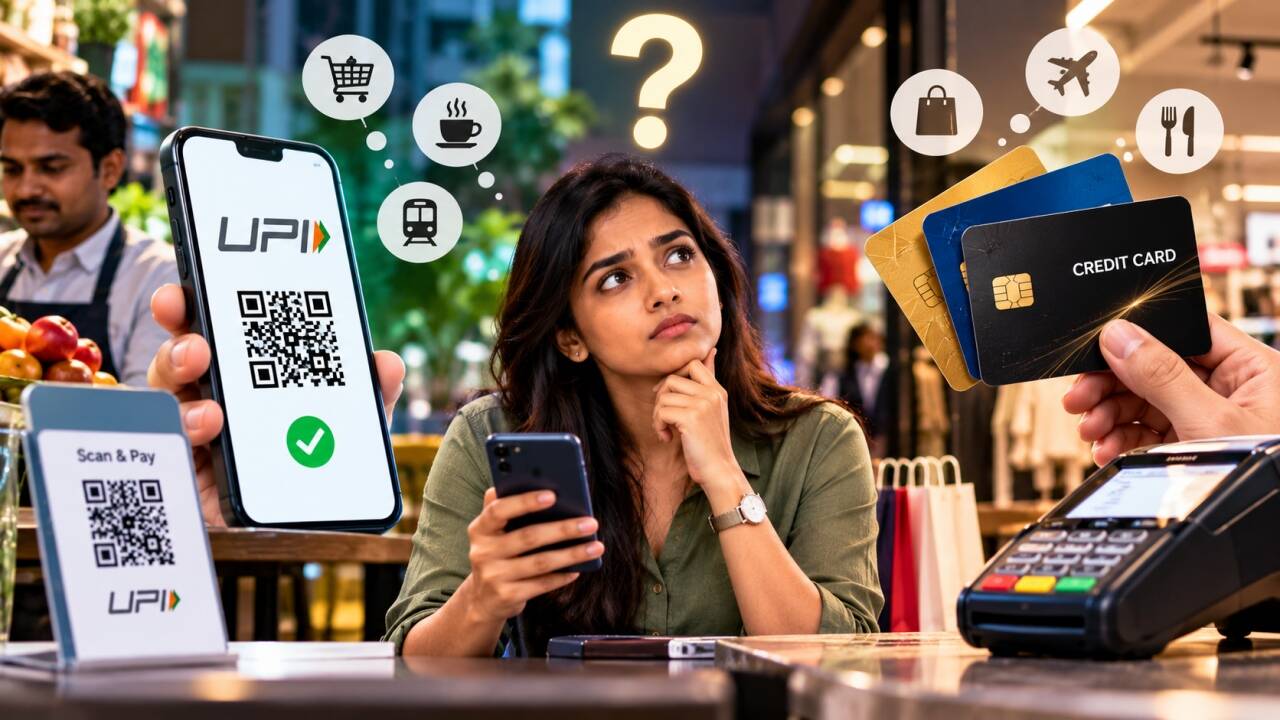
The Reserve Bank of India is revisiting the Merchant Discount Rate (MDR) that merchants pay for each transaction. While UPI payments have largely been exempt from MDR for low‑value trades, recent proposals could introduce a modest fee. At the same time, credit‑card MDR continues to vary by card type, and RuPay credit cards are now being linked to the UPI network, blurring the line between the two payment modes.
For investors, the cost structure of payments matters because it influences merchant margins, pricing strategies and the volume of transactions processed through different channels. A shift toward lower‑cost UPI or higher‑cost credit‑card usage can affect the earnings of banks, payment processors and card‑network operators that earn a share of the MDR.
Watch for the RBI’s final MDR guidelines, the speed of RuPay credit‑card adoption on UPI, and any merchant‑level responses such as changes in pricing or a preference for one payment method over another, as these will shape the competitive dynamics of India’s payments ecosystem.
Excerpt from Times of India
UPI vs credit cards: What should you choose for payments after MDR? UPI and cards serve different purposes in the consumer wallet Value-back as rewards or cashback can change the economics Transaction size alone does not determine the better choice Credit cards can offer value beyond the immediate transaction The…Read the original at Times of India
Key takeaways
- Category: Economy.
- Assessed as a significant, market-relevant update.
Why it matters
A meaningful update worth tracking. Use the price and stock snapshot to gauge how the market is responding.